Direct Express® Mobile

Screenshots
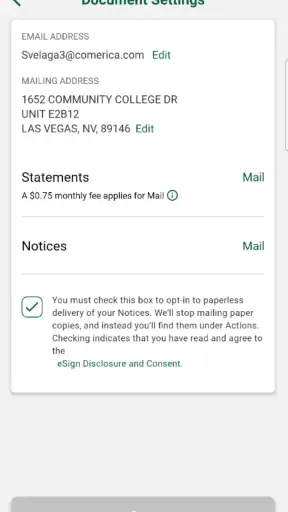
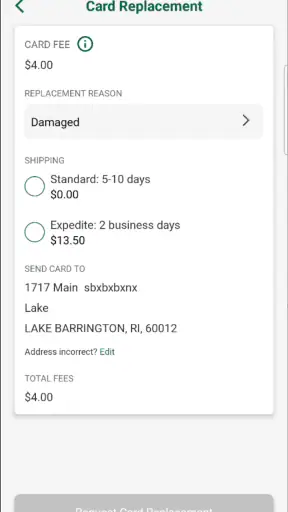
Details
- Rating
- 21.27K reviews
- Version
- 9.4
- Developer
- Fifth Third Bank
Analysis by Norviv
Managing federal benefit money is different from choosing an ordinary banking app. The important question is not whether an app looks impressive, but whether it helps me check available funds, understand card activity, and handle everyday spending without adding confusion. Direct Express® Mobile is built around that narrower job. It is a free finance app from Fifth Third Bank connected to the Direct Express® prepaid debit card, which is offered to federal benefit recipients.
After using it as a practical money-management tool, I see the main appeal clearly: it keeps attention on the card and the balance rather than trying to become a complete replacement for every banking service. That focus can be reassuring when I mainly need to know whether a payment is safe to make. At the same time, anyone expecting a full-service checking account experience should approach it with different expectations.
What I would consider before choosing it
My first decision criterion would be eligibility and purpose. This is not a general-purpose budgeting app that I would recommend to every smartphone owner. Its role is tied to the Direct Express® card, so it makes the most sense for a federal benefit recipient who uses that card for regular purchases and wants mobile access to card information. If I did not have that card, the app would not be a useful standalone finance tool for me.
The second criterion is simplicity. I would ask myself whether I need a focused way to keep an eye on card funds or whether I need broader services such as checking-account management, savings tools, bill organization, or detailed spending analysis. Direct Express® Mobile is easier to understand when I judge it against the first need. Comparing it directly with a full bank app can be misleading because the products serve different financial arrangements.
It is also worth considering phone compatibility before making the switch to mobile management. The app supports devices running Android 9 or later, which covers many users but still matters if an older phone is being kept for reliability or affordability. I would check the operating system before planning around the app, especially if the phone is several years old.
Trust and familiarity may influence the decision too. Fifth Third Bank is the developer, while the card itself is the center of the experience. That relationship is useful for people who want their card activity handled within an app associated with the service, rather than relying on an unrelated personal-finance tracker. I would still keep normal account-security habits: use a private device, protect the phone, and avoid signing in while connected to a network I do not trust.
A focused way to check the card during ordinary days
The strongest everyday use case is simple. Imagine I am preparing to buy groceries near the end of the week. Instead of guessing whether the card can cover the purchase, I open the app and check the available balance before leaving home. That small step can prevent an awkward declined transaction and gives me a clearer picture of what money remains for transportation, food, or other necessities.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
I also find a focused card app more useful when I make several small purchases. A benefit payment can be spread across groceries, pharmacy items, household supplies, and recurring expenses. Checking the app after those transactions helps me connect actual spending with the balance I see, rather than relying on memory. The value is not sophisticated financial planning; it is reducing uncertainty at the moment I need an answer.
Another practical workflow is to review activity after a purchase that seems delayed or unfamiliar. I would use the app as an early checkpoint: look at the card information, compare the entry with my receipt, and decide whether I need to investigate further through the appropriate support channel. This is more useful than waiting until the end of the month and trying to reconstruct every transaction from memory.
For a caregiver or family member helping someone manage benefit spending, the app may also make routine checking easier, provided the cardholder controls access appropriately. I would not share passwords casually or leave a logged-in phone unattended. The convenience of mobile access should not turn into an informal arrangement where several people handle sensitive financial information without clear boundaries.
Why the focused design can be a strength
In my experience, financial apps become tiring when they present too many unrelated tools before showing the one thing I need. Direct Express® Mobile has a more specific identity. I open it because I want card-related information, not because I want to connect investments, compare loans, or build a long-term portfolio. That narrower purpose can make the app less intimidating for someone who does not want a complicated financial dashboard.
The app is free, which removes one obvious barrier to trying it. I would still separate the app’s price from the broader costs or rules associated with using a prepaid debit card. “Free” describes the app itself; it should not be interpreted as a promise that every card-related action or service is free. Before relying on a particular transaction method, I would review the terms that apply to my card and situation.
Its public reception also suggests that many people find the service useful. The app holds an average rating of 4.6 from around 192 thousand ratings, and it has passed one million installs. I treat those figures as encouraging rather than conclusive. A strong average can show that the basic experience works for many cardholders, but it cannot guarantee that every login, device, or transaction will feel equally smooth.
The age classification is Everyone, which fits the app’s practical financial purpose. That does not mean every child should use it independently; card access and benefit management are adult responsibilities in most real situations. It simply indicates that the app’s content is not presented as mature entertainment or restricted material.
Small habits that make the app more useful
My first tip is to check the balance before, not after, a planned purchase. That sounds obvious, but it changes the app from a record of past activity into a decision tool. If I am buying several essentials, I can confirm the available amount first and avoid treating an old remembered balance as current.
My second tip is to use receipts and the app together. A receipt tells me what a merchant says I paid; the app helps me compare that information with the card activity. Keeping both for important purchases creates a simple personal audit trail without requiring a separate budgeting service. I would pay particular attention to unfamiliar descriptions or amounts that do not match what I expected.
My third tip is to make a routine around benefit deposits and recurring spending. I would check the card after the money arrives, note the major obligations I expect to cover, and then revisit the app after larger purchases. This is not a complete budget, but it creates a lightweight sequence: confirm funds, spend intentionally, and review what changed.
A fourth useful habit is deciding what the app should not do. I would not use it as my only record of financial planning, especially if I need to track cash, another bank account, or debts. A simple notebook or separate budgeting tool may still be necessary. The app works best when I give it one clear responsibility instead of expecting it to organize my entire financial life.
Where a different kind of app may fit better
The usual alternative is a full-service bank app. That type of app is a better fit for someone who wants several accounts in one place, transfers between checking and savings, broader account management, or a more complete view of household finances. I would choose that route if my daily money is spread across multiple banking products and I need one central dashboard.
A budgeting app is another alternative, but it solves a different problem. Budgeting tools are generally more useful when I want categories, spending trends, goals, or a combined view of cash and accounts. Direct Express® Mobile is the better choice when the immediate question is card availability and activity. A budgeting app may be better when the question is why my money disappears over a month and how to change that pattern.
A prepaid-card app from another provider may appear similar, but switching simply for a different interface would not make sense if my federal benefits already arrive through Direct Express®. The card relationship matters more than cosmetic differences between apps. I would compare alternatives only if my eligibility, payment arrangement, or broader banking needs had changed.
There is also the option of using non-mobile support or a physical record. That may suit someone with an older phone, limited data access, or discomfort with financial apps. Mobile convenience is valuable, but it is not a requirement for responsible money management. If an app creates more stress than clarity, a dependable offline routine can be the better choice.
The main limitation I notice is scope. The app is not something I would install expecting extensive financial education or a complete household budget. Its focused nature is its advantage and its boundary at the same time. Someone who wants investment information, detailed forecasting, or a unified view of unrelated accounts should look toward a different category rather than judging this app harshly for staying centered on Direct Express®.
What switching to mobile management involves
The cost of switching is not mainly financial because the app itself is free. The real cost is learning a new routine and deciding how much I want to depend on a phone for card checks. I would begin by installing it on a supported device, completing the required access steps carefully, and making sure I can protect the phone and credentials. I would not uninstall another trusted method until I had confirmed that the mobile routine works for me.
I would also plan for moments when the phone is unavailable. A dead battery, lost device, forgotten credentials, or poor connectivity can interrupt access at an inconvenient time. That does not make the app unsuitable, but it means I should know how I will verify important information when mobile access is not practical. Keeping essential contact and card details in a secure place is a sensible backup step.
Switching can change how often I look at my finances. That is helpful if regular checks prevent surprises, but it can become unproductive if I repeatedly refresh the app without a clear purpose. I prefer a schedule connected to real events: before a large purchase, after a benefit payment, and when a transaction needs checking. This keeps the app useful without turning it into a source of constant worry.
Privacy is another part of the transition. I would avoid using a shared phone profile for financial access, lock the device, and be cautious about messages that ask for credentials. The app can simplify access to card information, but convenience also means the phone becomes an important gateway. Good device habits are part of using the service responsibly, not an optional extra.
The current version is 9.4, and the app was released on December 4, 2021. I mention those details because they help place the product in context: it is an established mobile service rather than a brand-new experiment, while continued updates still make it sensible to keep the app and phone software maintained. I would install updates through the normal platform process and review the app after major phone changes.
My recommendation for the right cardholder
I recommend Direct Express® Mobile to a Direct Express® cardholder who wants a straightforward way to check card information while going about daily life. Its best quality is focus. It can help me make a purchase with more confidence, review activity while details are fresh, and build a simple habit around benefit spending without requiring a full banking setup.
I would not recommend it as the main financial app for someone who does not use the Direct Express® card, or for someone seeking advanced budgeting and multi-account management. In those cases, a full-service bank app or dedicated budgeting tool is likely to fit better. The decision should follow the job I need done, not the app’s rating or the fact that it is free.
Overall, I see it as a practical companion to the card rather than a universal replacement for banking. Its audience is specific, and that specificity is exactly why it can be useful. If my priority is knowing what is available on my Direct Express® card and keeping everyday spending under control, I would choose it. If my priority is managing a complete financial picture, I would pair it with another tool or select a broader alternative.
For eligible users, the best way to judge it is to start with one concrete routine: check the balance before a planned purchase, compare activity with receipts afterward, and see whether that reduces uncertainty. If it does, the app is doing its job. If I still need extensive planning, account aggregation, or detailed analysis, I would keep this focused card access but add a service designed for those specific needs.
Frequently Asked Questions
01What is Direct Express® Mobile used for?
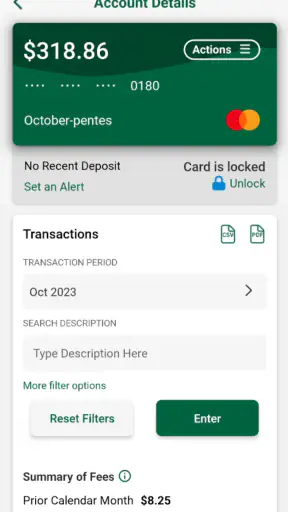
Direct Express® Mobile is the official mobile app for eligible Direct Express cardholders. After signing in, users can review their available balance, check recent transactions, monitor deposits, locate nearby ATMs, and manage certain card-related services. It is designed to provide convenient access to account information without requiring users to visit a website or call customer service for every routine request.
02Who can use the Direct Express® Mobile app?
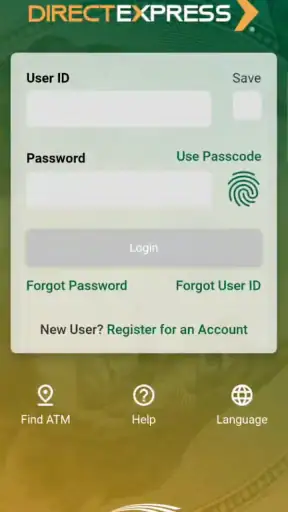
The app is intended for people who have an active Direct Express card account, generally used to receive federal benefit payments electronically. You normally need your card or account credentials and other identifying information to register or sign in. If you do not have a Direct Express card, access may be limited, and downloading the application alone does not create an account or make you eligible for the program.
03Is Direct Express® Mobile safe to use for checking my card account?
The application is built to provide protected access to Direct Express account information, with sign-in security and safeguards intended to help prevent unauthorized access. Nevertheless, users should download it only from the official Google Play Store or Apple App Store, keep the app and operating system updated, avoid sharing passwords or verification codes, and never sign in through suspicious links sent by email, text message, or social media.
04Can I use the app to transfer money, withdraw cash, or manage my card?
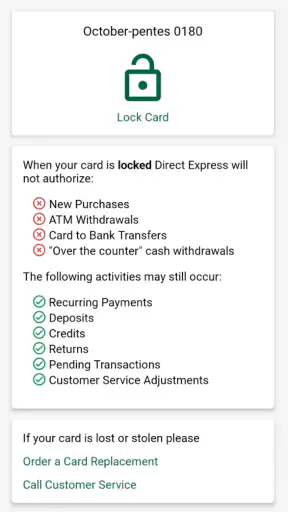
Direct Express® Mobile is primarily useful for viewing account details, transactions, deposits, and locating participating ATMs. The exact services available may depend on your account status and current program rules. Some actions, such as cash withdrawals, card replacement requests, disputes, or broader account assistance, may require an ATM or contact with Direct Express customer service rather than being completed entirely inside the app.
05What should I do if I cannot log in or notice an unfamiliar transaction?
First, confirm that you are using the correct login information and the latest version of the official app. Use the available password or account-recovery options rather than repeatedly guessing credentials. If you see an unfamiliar transaction, suspect fraud, lose your card, or believe someone accessed your account, contact Direct Express through the official customer-service channels as soon as possible and avoid sharing sensitive information with anyone claiming to offer unofficial support.


